What to take into your next appraisal
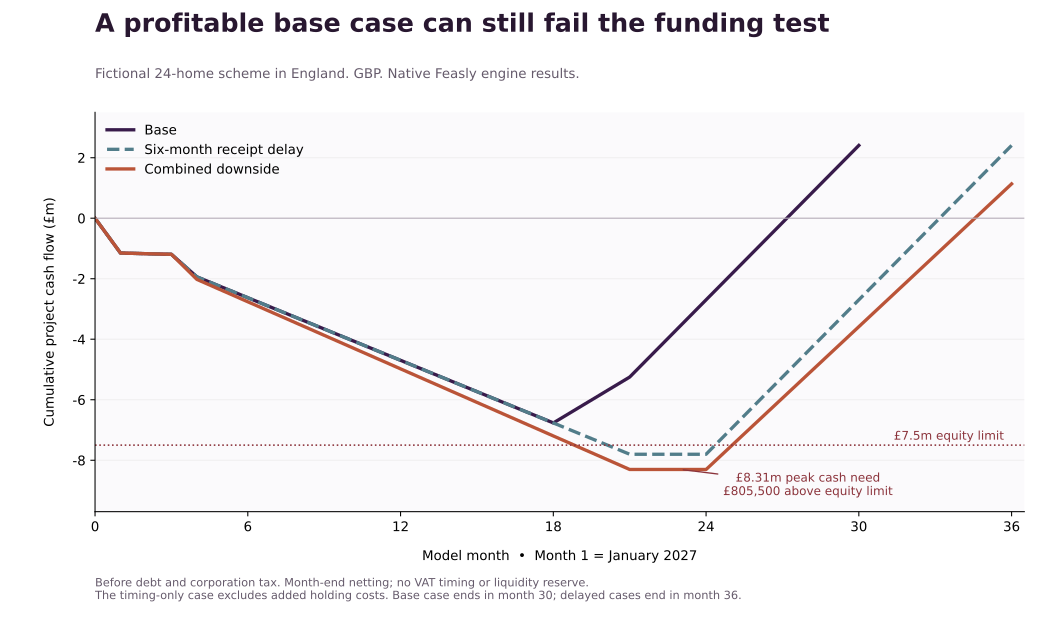
- The base case makes £2.41m before debt and corporation tax, with £6.77m peak project cash need.
- A six-month receipt delay leaves nominal profit unchanged in the timing-only test but raises peak cash need to £7.80m.
- The combined downside needs £8.31m, leaving £805,500 unfunded against the illustrative £7.5m equity limit.
The instruction: test the purchase before committing
This is an invented commercial appraisal, prepared by Feasly for explanation. It is not a customer case, a valuation, a planning viability submission or evidence of current UK prices. The site has no real address or comparable transactions. All amounts are GBP; the assumed model starts in January 2027.
The fictional developer proposes 24 freehold houses for open-market sale. Assume a consented scheme with its tenure mix and cash planning obligations already agreed. That is a scenario condition, not a claim that a 24-home scheme normally avoids on-site affordable housing. If the actual permission requires affordable homes or a different mix, rebuild the revenue and delivery assumptions before relying on this case.
For this exercise only, the investment committee requires at least 20% profit on total modelled cost before debt and corporation tax, and has a £7.5m all-equity capital limit. Neither is an industry standard or a planning-policy benchmark. The land price is a fixed input, not a residual valuation.
Reconcile the homes, areas and sales receipts
The schedule assumes 2,480 m² of internal house area. The construction rate is applied to that same stated area; it is not a site-area or net-to-gross efficiency calculation. Prices are invented agreed-underwriting assumptions, with no house-price growth. They must be replaced by an evidenced sales schedule for a real instruction.
GDV is £10.44m before selling expenses. There is no retained rental investment, commercial component, purchaser incentive or separate parking receipt in this example. Each of those would need explicit treatment if present.
| House type | Homes | Area per home | Price per home | Total receipts |
|---|---|---|---|---|
| Two bedroom | 8 | 85 m² | £350,000 | £2,800,000 |
| Three bedroom | 12 | 105 m² | £440,000 | £5,280,000 |
| Four bedroom | 4 | 135 m² | £590,000 | £2,360,000 |
| Total | 24 | 2,480 m² in total | £435,000 weighted average | £10,440,000 |
Make the cost plan reconcile to £8,034,300
Main works are £4.96m, using the invented £2,000/m² rate, plus £400,000 infrastructure and £190,000 abnormal works. These form the £5.55m construction input. Professional fees are £444,000; contingency is £277,500. Both are explicit allowances, not values supplied by the engine.
Land acquisition includes a £1.05m price, a £42,000 SDLT allowance and £38,000 legal, agency and due-diligence costs. The SDLT allowance assumes a non-residential freehold acquisition with no VAT on the price and no relief or linked transaction. Its rate basis was checked against HMRC guidance on 13 October 2026. Classification and tax treatment would need confirmation for an actual purchase.
The £400,000 other-cost allowance comprises £250,000 planning contributions, £80,000 site holding and utilities, and £70,000 warranties and insurance. All are invented budgets. The contribution assumes any affordable-housing obligation is already resolved through the stated consent. It is not a local authority tariff or evidence that this payment would discharge a real obligation.
Selling costs are 2% of gross receipts plus £1,000 legal cost per home. This keeps the £24,000 fixed component unchanged when prices fall. Contingency is fully spent in every modelled case, so unused contingency is not quietly counted as extra profit.
| Cost input | Base budget | Timing in the model |
|---|---|---|
| Land and acquisition | £1,130,000 | Month 1 |
| Construction, infrastructure and abnormals | £5,550,000 | Months 4 to 21 |
| Professional fees | £444,000 | Months 1 to 21 |
| Contingency | £277,500 | Months 4 to 21 |
| Selling costs and disposal legal fees | £232,800 | Months 19 to 30 |
| Other development costs | £400,000 | Month 4 |
| Total modelled cost | £8,034,300 | Before debt and corporation tax |
Sources: HM Revenue & Customs: SDLT rates for non-residential and mixed land and property
Follow the programme into cash
Months 1 to 3 cover acquisition and mobilisation. Construction expenditure runs evenly from month 4, April 2027, through month 21, September 2028. The first completed homes produce receipts from month 19, July 2028. Selling continues over 12 months to month 30, June 2029.
The model receives one twelfth of GDV each month during that sales window. This is equivalent to two homes a month at the weighted average price, not an asserted plot-by-plot handover schedule. Sales overlap the last three construction months, so the assumed first releases must be physically deliverable with access, services and approvals in place.
Fees, construction, contingency and selling costs are spread evenly within their own windows. The other-cost allowance is charged in month 4 as a deliberately early, simplified cash assumption. There are no spend curves, retentions, phased contributions or separate deposit receipts. Month-end receipts offset costs in the same month, which can understate the cash needed between payment dates.
| Cash milestone | Base case | Six-month receipt delay |
|---|---|---|
| Land payment | January 2027 | January 2027 |
| First receipts | July 2028 | January 2029 |
| Last receipts | June 2029 | December 2029 |
| First month of maximum funding need | June 2028 | September 2028 |
| Peak month-end project cash need | £6,766,821 | £7,801,500 |
Test the risks separately, then together
The Feasly Calculation Engine calculates all five cases. The table rounds cash to the nearest pound; the downloads include the unrounded results and monthly cash flows.
The price case cuts every sale price by 7.5%. The construction case increases the full £5.55m construction budget by 8%, adding £444,000. Professional fees and the £277,500 contingency budget stay fixed. The increase is additional to the fully modelled contingency, not an assumed draw from it.
The timing-only case shifts receipts and selling costs six months later while keeping their totals and all other spending unchanged. That deliberately isolates timing. It does not suggest a real delay is free. The combined case applies all three changes and adds a separate £60,000 stock-holding allowance, charged early within other costs. It still excludes finance charges.
| Case | Profit | Profit on cost | Peak cash need | First peak month |
|---|---|---|---|---|
| Base | £2,405,700 | 29.94% | £6,766,821 | 18 |
| Sales prices down 7.5% | £1,638,360 | 20.43% | £6,766,821 | 18 |
| Construction budget up 8% | £1,961,700 | 23.14% | £7,136,821 | 18 |
| Receipts six months later | £2,405,700 | 29.94% | £7,801,500 | 21 |
| Combined, plus £60,000 holding cost | £1,134,360 | 13.31% | £8,305,500 | 21 |
The decision: the base case fits, the downside does not
The £7.5m illustrative equity limit exceeds the base peak by £733,179. A timing-only delay changes the position to a £301,500 shortfall, even though reported nominal profit remains £2.41m. In the combined case, the shortfall grows to £805,500 and profit on cost falls below the stated 20% requirement.
The delay case first reaches its peak in month 21 and stays there through month 24, before sales start in month 25. A single peak-month label hides those four month-end observations at the same maximum funding requirement. Review both the height and the duration of the cash exposure.
For this fictional committee, the appropriate decision is conditional progression, not an unconditional land commitment. The base case justifies further work. Approval would still require a credible response to the combined return and funding failure, backed by evidence: a revised purchase price or scheme, lower verified costs, deliverable release dates, or additional capital on acceptable terms.
A debt facility cannot simply be subtracted from peak project cash need to produce peak equity. A financed appraisal needs draw eligibility, equity-first or pro-rata funding, facility limits, retained interest, fees, sales-release conditions and repayment timing. None is modelled here. The £7.5m comparison assumes unrestricted equity and full recycling of sales receipts; it is not a lender commitment or a levered equity return.
What the development manager needs before approval
This budget and timing example uses fictional inputs. Before relying on a real project appraisal, resolve the following decision conditions.
| Evidence owner | Required evidence | Consequence if unresolved |
|---|---|---|
| Sales adviser | Plot-level comparable evidence, incentives and absorption schedule | Revise GDV, selling costs and receipt timing. |
| Cost consultant and contractor | Cost-plan scope, tender position, abnormals, exclusions and spend curve | Revise the construction budget and cash profile; reconcile contingency. |
| Planning and legal team | Consent, tenure obligations, contributions, conditions and tax classification | Rebuild any invalid scheme, obligation or acquisition assumption. |
| Development manager | Achievable phased handovers, utilities, access, building control and warranty approvals | Do not retain month 19 receipts without a deliverable release plan. |
| Finance and tax advisers | Funding terms, VAT recoverability and repayment timing, corporation tax and liquidity reserve | Complete the financed and tax cash flow before investment approval. |
Ask which question the appraisal must answer
A developer deciding whether to buy land needs to test an investment using its proposed scheme, delivery approach and return requirement. A planning adviser considering viability is working within the relevant planning framework. A valuer giving an opinion of value has a defined assignment, basis and date. Reusing a model may be sensible, but reusing its conclusion without checking the instruction can mislead the next reader.
RICS explains that scope, purpose and basis matter when determining what a figure represents; a label alone does not settle whether advice is a valuation. Start the brief with the client, intended use, property interest, information date and decisions expected from the report. Record who is permitted to rely on it and the limitations agreed for that instruction.
| Instruction | Main question | Check before reuse |
|---|---|---|
| Commercial development appraisal | Does this proposal meet the developer's decision criteria? | The developer's costs, delivery assumptions and target return. |
| Planning viability assessment | How does the case address the applicable planning requirements? | The jurisdiction, current policy, relevant evidence and assessment scope. |
| Valuation assignment | What is the value on the instructed basis and date? | Terms of engagement, basis, assumptions and professional requirements. |
Sources: RICS: When is a figure a valuation? Understanding scope, purpose and basis under Red Book
Name the jurisdiction behind planning assumptions
The National Planning Policy Framework published on GOV.UK applies to England. Its current publication page identifies an August 2026 framework. Do not assume that an older English template, paragraph reference or planning allowance governs a present instruction elsewhere in the UK. Identify the relevant nation, local authority, adopted policies and site-specific obligations with the planning team.
England's Planning Practice Guidance on viability describes a planning assessment using development value, costs, land value and developer return. It also addresses the evidence and presentation expected for that purpose. These are planning-context considerations, not a universal commercial investment hurdle. Read the current framework and supporting guidance together, and resolve the requirements applicable to the particular submission before fixing the model specification.
Sources: Ministry of Housing, Communities and Local Government: National Planning Policy Framework; Ministry of Housing, Communities and Local Government: Planning Practice Guidance: Viability
Inspect and reproduce the calculation
The download contains the assumptions, calculated results and monthly cash flow for each of the five cases. Use it to compare the separate effects of lower sales, higher costs and delayed receipts. The data describes this example; it is not a saved Feasly project or an import template.
To reproduce the base case in Quick Feasibility, choose GBP, enter the stated revenue and cost totals, then set the category start months and durations from this guide. Use land and acquisition of £1.13m, not the £1.05m purchase price alone. Set a January 2027 calendar start for the same labels. Keep all five cost categories visible, including other costs. The JSON files include the inputs and unrounded results for each case.
Use the chart and downloads to explore the financial consequences of the stated assumptions. The fictional scheme and decision thresholds are not UK market benchmarks.
Try the method with your own assumptions
Enter the GBP assumptions and category timing from this guide. Inspect the monthly cash flow before adding debt, tax cash flows or a liquidity reserve.
Reproduce the worked appraisalSources and further reading
- When is a figure a valuation? Understanding scope, purpose and basis under Red Book RICS
- National Planning Policy Framework Ministry of Housing, Communities and Local Government
- Planning Practice Guidance: Viability Ministry of Housing, Communities and Local Government
- Valuation of development property RICS
- SDLT rates for non-residential and mixed land and property HM Revenue & Customs
Published by Feasly. How we prepare our guides. Suggest a correction.