What to take into your next appraisal
- A national market indicator cannot establish demand or pricing for a specific development.
- Distinguish building approval, developer qualification and an applicable off-plan project licence.
- Use current transaction-specific tax and funding assumptions, with clear responsibility for verification.
Define the site and the route to development
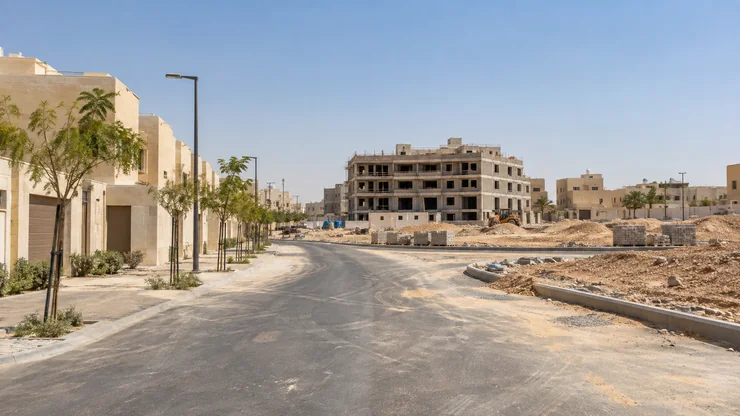
Start with the land interest, development entity, intended asset and responsible authority. Establish the permitted use and governing conditions. A residential project should not inherit an industrial model simply because both are in Saudi Arabia. The land, infrastructure, customer and approval evidence must match the investment.
Prepare a responsibility map covering the landowner, developer, designers, contractor, funders and any operating partner. Identify which assumptions require a document, an authority response or a professional opinion. Where rights or approvals are not settled, show that dependency before calculating an unconditional land bid. An unresolved permission is different from a cost estimate with a reasonable range, and the model should make the distinction clear.
Test demand at the level of the proposed asset
GASTAT describes its Real Estate Price Index as a measure of price movements over time, with breakdowns by sector, property type and geography. Such evidence helps place a proposal in context. It does not directly establish an achievable sales price, rental level or absorption rate for a particular unbuilt scheme. Use the index as context and maintain a separate, dated schedule of relevant comparables.
Define the intended customer and compare location, size, specification, accessibility and payment terms. For a rental project, investigate income after incentives and vacancy. For a sold development, separate launch demand from the pace of collections. Explain the evidence and its limitations. A national growth narrative still needs support at project level.
Connect approvals to the programme
Balady publishes a building-permit process involving the owner or representative, design office, technical review and municipal stages. Its service requirements identify items such as land documentation, a cadastral report, design and supervision arrangements and project studies where applicable. Confirm the precise route with the competent authority and appointed design team, including any additional approvals for the proposed activity.
Convert that route into a dependency schedule: which design decision or document enables the next step, who owns it and when evidence is expected. A portal service duration is not the total time required to acquire land, complete design, resolve comments and prepare a compliant application. Keep application preparation, review, construction, inspections and operational readiness distinct. Test the cash consequence of a delayed dependency rather than adding the same delay to every activity.
Model the applicable off-plan route explicitly
For a scheme involving off-plan sale or lease, review the applicable REGA requirements separately from the building permit. REGA lists qualification and project licensing services, and its project-licence guidance includes an economic feasibility study and an escrow-account agreement. Establish which requirements apply to the project and obtain the current conditions before assuming that a planned marketing or collection date is achievable.
The model should distinguish reservations, signed agreements, scheduled payments, cash received and amounts available for project use. Have the advisers and account bank confirm the relevant controls and release evidence. Do not infer unrestricted funding from the value of contracted sales. Keep any marketing permissions distinct from the permission and conditions for selling or leasing the particular project. This is a project-specific check, not a statement that all Saudi development follows one sales structure.
Sources: Real Estate General Authority, Saudi Arabia: Off-Plan Sales and Lease
Price the scope that must actually be delivered
Build a cost plan around the actual design, ground conditions, procurement route and delivery responsibilities. Separate site preparation, primary construction, external works, utilities, professional services, authority costs and commissioning. Record whether each allowance includes supply, installation, logistics and testing. Where the development interfaces with a wider infrastructure programme, establish who delivers each connection and when it becomes available.
Document quotation dates, scope and exclusions. A cost per square metre needs a matching area basis and specification. Schedule advances, progress payments and retention. A delayed utility connection or commissioning package can affect income even when the main building is substantially complete. Identify that dependency and its owner before deciding the appropriate contingency or funding reserve.
Verify tax treatment using the current transaction structure
Separate the land transaction, development expenditure, sale or lease income and investor distributions when asking for tax advice. ZATCA states that the current Real Estate Transaction Tax Law took effect on 10 April 2025. A saved model using an earlier note should therefore be reviewed against the applicable current law and implementing rules, not carried forward solely because its formulas still calculate.
Record the relevant entity, transaction, assessment basis, possible relief or exemption, required evidence and payment timing. Address VAT and any entity-level tax obligations separately where applicable. Show recoverability and its expected timing rather than treating every tax cash payment as a permanent cost. This guide deliberately supplies no universal tax allowance: ownership, contracts and transaction facts must support the treatment entered into the particular feasibility.
Sources: Zakat, Tax and Customs Authority: Real Estate Transaction Tax Law
Match capital to the cash programme
Translate the proposed financing documents into period cash movements. Record the equity contribution sequence, eligible expenditure, draw conditions, financing charges, reserves and repayment obligations. If a financing structure uses different contractual terminology or mechanics, model the actual obligations rather than forcing them into a generic loan template. Keep the project cash schedule separate from the investor distribution schedule so returns can be interpreted consistently.
For a phased project, test whether later phases depend on earlier receipts and whether shared infrastructure needs funding first. For a retained asset, include occupancy and refinancing dependencies. Compare maximum funding need with committed resources, then stress when funds become available. Report the period of the largest shortfall alongside the final profit or investment return.
Present the dependencies that can change the decision
Issue a base case with a dated evidence register, then show the effect of the uncertainties most relevant to the site: delivery delay, slower sales or lease-up, changed construction scope, lower pricing or later funding availability. Combine related assumptions into coherent scenarios. Identify the switching point at which the team would revise the land offer, stage the commitment or require additional capital.
Give unresolved conditions an owner and next action. Preserve the approved version so the investment committee can see why the forecast moved. Keep the appraisal useful through design and delivery, with legal, planning, engineering, valuation and tax conclusions established for the particular location and transaction.
| Dependency and evidence | Model connection | Review action |
|---|---|---|
| Land rights, design basis and the applicable building approval record | What can be delivered and which activities can start | Design lead confirms the responsible authority, missing inputs and programme sequence. |
| Developer qualification and project licence for an applicable off-plan route | Commercial launch and collection assumptions | Project advisers check the relevant REGA route separately from building approval. |
| Account agreement and project-specific release evidence | Collected cash versus cash available for project expenditure | Finance lead and account bank verify the restrictions and timing used. |
| Utility or shared-infrastructure delivery commitments | Connection costs, commissioning and income start | Development manager records who delivers the connection and tests a later availability date. |
Sources: Balady Platform: Issuing a Building Permit; Real Estate General Authority, Saudi Arabia: Off-Plan Sales and Lease
Sources and further reading
- Methodology and Quality Report for Real Estate Price Index Statistics 4.1 General Authority for Statistics, Saudi Arabia · Accessed 15 September 2026
- Issuing a Building Permit Balady Platform · Accessed 15 September 2026
- Off-Plan Sales and Lease Real Estate General Authority, Saudi Arabia · Accessed 15 September 2026
- Real Estate Transaction Tax Law Zakat, Tax and Customs Authority · Accessed 15 September 2026
Published by Feasly. How we prepare our guides. Suggest a correction.